 Grant Thornton plans $2 billion in junk bonds at almost twice the price CBIZ was paying.
By CPA Trendlines Research
After a mountain of debt sent pioneering tax and accounting consolidator CBIZ looking for a suitor, Grant Thornton stepped up. Now Grant Thornton itself is looking to place $2.25 billion in junk bonds to help pay for the $5-billion deal.
MORE Special Report on the CBIZ-Grant Thornton Deal:
The saga comes to a head next week when CBIZ shareholders vote on the $55-a-share cash offer from Grant Thornton Advisors, the private equity-backed non-attest platform.
CBIZ shareholders are approaching the decision with new evidence of both the CBIZ’s recovery and GT’s financing plans.
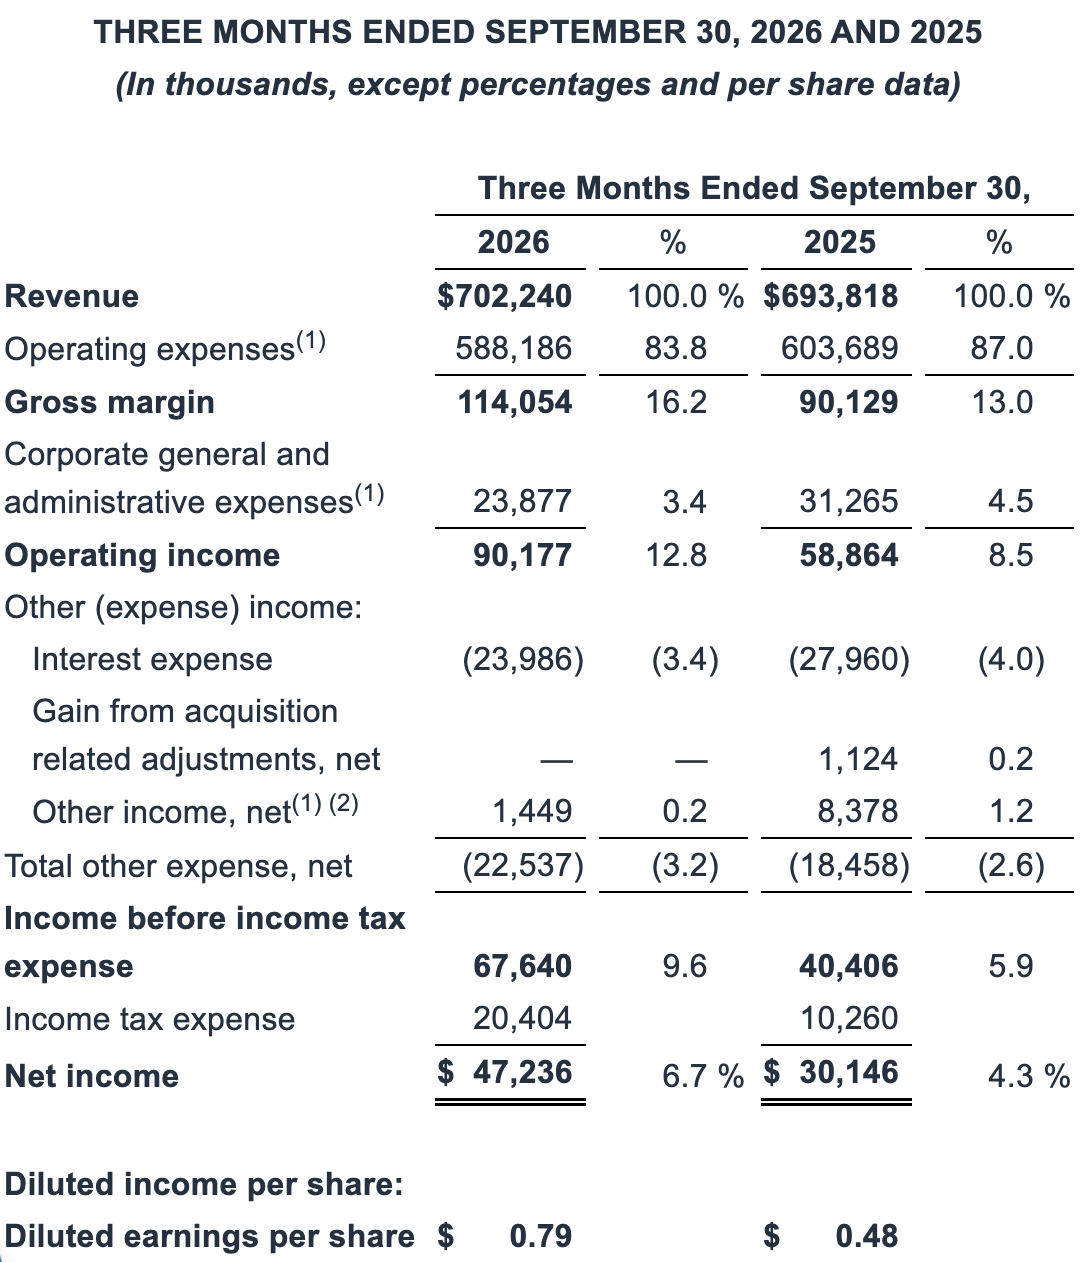
In the just-released third-quarter report, CBIZ profit rises sharply as CBIZ works off expenses from its costly Marcum deal in 2024.
GT’s first junk bonds foray calls for $1.75 billion of dollar notes and $500 million-equivalent of Euro notes, according to Wall Street sources. Grant Thornton Advisors and backer New Mountain Capital are now borrowing far more to absorb the business into a larger platform. GT will be clearing away CBIZ debt only to take up the obligations, even as Fitch rates GT speculative grade.
The irony is not lost on observers noting CBIZ debt rose sharply with its Marcum acquisition and stunted CBIZ’s historically aggressive acquisitions program, which forced the company into a sale, or that GT is paying almost twice the interest rate CBIZ had been paying.
Marcum enlarged the business and the borrowing
CBIZ’s Marcum acquisition transformed its scale. Revenue rose 52.1 percent in 2025 to $2.758 billion, but newly acquired operations, net of divestitures, supplied $914.2 million of the $944.5 million increase, or about 96.8 percent of the gain.
Borrowing under CBIZ credit facilities reached $1.472 billion at the end of 2025, compared with $312.4 million under an unsecured facility two years earlier. Annual interest expense rose to $107.2 million from $34.4 million in 2024.
After Marcum, paying down debt to a net leverage ratio below 2.5 times was the company’s stated second priority, behind funding organic growth. The definitive merger proxy, in listing the stand-alone alternatives the board weighed, includes “using divestiture proceeds to reduce indebtedness and create capacity for share repurchases or strategic acquisitions.” The board also notes that the company’s actual results had recently fallen short of its projections.
Progress on the debt had been slow. Gross credit-facility borrowings stood at $1.454 billion on Sept. 30, down $18.4 million from year-end, and the revolver balance was higher than in December. In the first half alone, CBIZ spent about $70 million repurchasing its own shares.
Reference Equity made leverage central to its activist campaign this summer, urging CBIZ to raise equity, cut leverage and restart acquisitions. After the deal was disclosed, portfolio manager Ryan Bunn called management’s decision a “capitulation.” Still, Bunn profited on CBIZ’s stock appreciation.
The sale talks also run on their own clock. According to the proxy, the board contacted Goldman Sachs in March for a preliminary view of the company’s valuation and strategic alternatives. A Grant Thornton representative called CEO Jerry Grisko on March 20, and Grant Thornton and New Mountain submitted a $55-a-share indication of interest June 8 — their fourth — a week before Reference’s June 15 letter, which the proxy does not mention.
A better quarter, built mostly on costs that are fading
CBIZ’s Oct. 19 results complicate the picture of a consolidator struggling after its largest acquisition, though less than the headline numbers suggest.
In the third-quarter report, revenue increases 1.2 percent to $702.2 million, while net income rises 56.7 percent to $47.2 million. Most of that gain comes from outside day-to-day operations. Pretax income rises $27.2 million. Lower Marcum integration costs account for $11.3 million of the increase, a one-time employee stock purchase plan correction credit for $5.9 million and lower interest expense for $4 million. Adjusted EBITDA, CBIZ’s measure of underlying operating profit, contributes $7.8 million. A higher tax rate absorbs part of the gain.
On that adjusted basis, the improvement is modest. Adjusted earnings before interest, taxes, depreciation and amortization increase 6.3 percent to $131.9 million, and the margin widens to 18.8 percent from 17.9 percent. Financial Services, the accounting and advisory core, supplies the operating gain, while Benefits and Insurance adjusted EBITDA declines. CBIZ originally reported third-quarter 2025 adjusted EBITDA of $120 million, before it began adding stock-based compensation back to the measure this year. Revenue and adjusted earnings per share also come in below analysts’ consensus estimates.
Buybacks add a further lift per share in the quarterly report. Diluted shares fall 4.3 percent from a year earlier, so GAAP earnings per share rise 64.6 percent, faster than net income.
The improvement follows a second quarter in which adjusted EBITDA fell 14.3 percent. The latest figures show quarterly profitability recovering while revenue growth remains modest.
For the first nine months, CBIZ revenue increases 0.8 percent to $2.233 billion. Before it withdrew its 2026 guidance on July 29, CBIZ projected full-year revenue growth of 2 percent to 5 percent. Nine-month adjusted EBITDA declines 1.2 percent to about $479 million.
The buyer’s capital has a cost
The financing behind the $55 offer is mostly borrowed. The proxy puts the total needed to complete the merger, including fees, at about $5.235 billion. Against that sit committed debt facilities of $4.4 billion, plus a $200 million revolving credit line, and up to $835 million of equity from New Mountain funds, including $200 million of convertible preferred equity with warrants. Bond proceeds reduce the $1.75 billion bridge loan dollar for dollar.
The dollar notes are being pitched at a yield of about 10.5 percent and the euro notes at about 9.5 percent, both due in five years, according to Bloomberg, which cites a person familiar with the matter. For comparison, CBIZ’s bank borrowing carried a blended average rate of 6.56 percent in 2025.
The ratings set the terms of the bet. Fitch assigns Grant Thornton Advisors a first-time BB- issuer rating and projects pro forma leverage of about 5.5 times EBITDA. The ratings “also reflect reliance on synergy execution to drive deleveraging,” Fitch says. Moody’s keeps its B2 rating with a stable outlook. Bloomberg counts more than $7 billion in loans and other financing in Grant Thornton Advisors’ capital structure.
New Mountain describes itself in the deal announcement as a firm that “emphasizes business building and growth, rather than debt.” Grant Thornton Advisors’ case is that scale pays for itself.
“Scale is going to matter because this is expensive,” CEO Jim Peko has told the media, discussing AI investment. He also rejects the market’s skepticism of the sector: “The market has it wrong. We’re seeing margin expansion in our business, and we’re also taking share.”
That sets up a continuing financial test. Access to financing makes the acquisition possible, while repayment and the firm’s $1 billion, three-year technology program both depend on the cash the enlarged operation generates.
The cash exit and the work that follows
The CBIZ virtual special meeting is set for 8 a.m. ET Oct. 27. Approval requires a majority of the 54,940,482 shares outstanding on the Sept. 16 record date, so a share not voted counts as a vote against. CBIZ’s board unanimously recommends approval, and proxy adviser Institutional Shareholder Services also backs the deal, Crain’s Cleveland Business reports. The antitrust waiting period expired Sept. 10. CBIZ continues to expect a fourth-quarter closing, but the vote alone does not complete the acquisition.
Under the announced structure, CBIZ’s Benefits and Insurance Services business becomes a separate company backed by New Mountain. Grant Thornton Advisors says the combination makes it the fifth-largest U.S. provider of professional services, tax and advisory services, with more than $5 billion in annual domestic revenue.
If the transaction closes, public shareholders take cash and give up any share of what comes next. Grant Thornton Advisors and its investors take on the job of turning greater scale, technology spending and integration into returns, with new notes marketed at yields well above what CBIZ paid on its bank debt as a public company.
CBIZ’s latest quarter shows that profit can recover as acquisition costs fade, even while revenue barely moves. The financing leaves the combined business facing a familiar demand: generate enough cash to keep investing while carrying the debt used to get bigger.
[
One Response to “Billions in Debt Decisions Dog CBIZ-Grant Thornton Deal”
Frank Stitely
Welcome back to the 1990’s when pretty much all the consolidators except for CBIZ fell apart.